

Buying a home or condo in Greater Cleveland starts with knowing your numbers. Use the calculator below to estimate your monthly payment, then get pre-approved with our go-to lender, Matt Sheffey of Keller Home Loans, so you can write a strong offer the moment the right home hits the market.
Get Pre-Approved with MattCall Matt (440) 668-2942
Cleveland Mortgage Calculator
Switch between a single-family home and a condo, then adjust the price, down payment, rate, taxes, insurance and HOA fee to see your estimated monthly payment.
Cuyahoga County's average effective property tax rate is roughly 1.9% a year, but it varies by city and school district. Condo fees vary widely by building and usually cover exterior maintenance, landscaping and snow removal.
- Loan amount
- $0
- Total interest
- $0
- Loan-to-value
- 0%
- Payoff
- —
Estimates for illustration only. The rate shown is an example, not a quote or offer, and actual rates, payments and terms depend on your credit, loan program and the property. Taxes, insurance, HOA and PMI amounts are estimates. Results exclude closing costs and fees. Not a commitment to lend; all loans subject to credit approval.
Meet Your Lender: Matt Sheffey
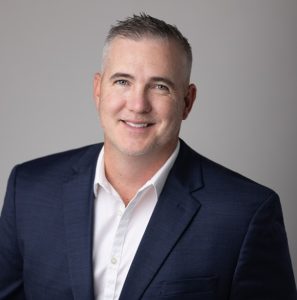
Our go-to lender
Matt Sheffey
VP of Sales, Keller Home Loans · NMLS #197990
Matt has been in mortgage lending since 2006, after five years as a commodities trader. He works side by side with the EZ Sales Team so our buyers get fast pre-approvals, clear answers and on-time closings across Greater Cleveland.
- Phone: (440) 668-2942
- Office: 18318 Pearl Road, Office 1, Strongsville, OH 44136
- Profile: kwlends.com/loan-officer/matt-sheffey
Why Get Pre-Approved First
- Stronger offers. Listing agents in popular Cleveland suburbs expect a pre-approval letter with every offer, and many sellers will not consider one without it.
- A real budget. You will know your price range and monthly payment before you fall in love with a house.
- Faster closings. Much of the paperwork is done up front, so you can close on time.
- No surprises. Credit or income questions come up early, while there is still time to fix them.
Loan Options
- Conventional: as little as 3% down for qualified first-time buyers; no PMI with 20% down.
- FHA: as little as 3.5% down with flexible credit guidelines.
- VA: no down payment for eligible veterans, service members and surviving spouses.
- USDA: no down payment in eligible rural areas, including parts of Lorain, Medina and Geauga counties.
- Jumbo: for homes above the conforming loan limit.
- Adjustable-rate (ARM): a lower starting rate if you plan to move or refinance within a few years.
- Refinance and cash-out: lower your rate or tap your equity once you own.
Ask Matt whether you qualify for Ohio Housing Finance Agency (OHFA) down payment assistance or first-time buyer programs.
Financing a Cleveland Condo
Condo loans review the association as well as you. Lenders look at the building’s budget and reserves, owner-occupancy rate, master insurance policy, rental rules and any pending litigation. FHA and VA buyers need an approved complex, or an FHA single-unit approval. Matt checks a building early so there are no surprises after your offer is accepted.
Researching downtown, lakefront or suburban condos? Our sister site MyClevelandCondo.com has building-by-building fees, rules and sales history.
Greater Cleveland Numbers to Plan With
- Median sale price: about $279,000 for the Cleveland area (July 2026, Homes.com).
- Property taxes: Cuyahoga County averages roughly 1.9% of value per year, but rates vary by city and school district. Check the county auditor’s figure for any home you are considering.
- Condo fees: vary widely by building and amenities; always review what the fee covers.
- Closing costs: plan on roughly 2% to 5% of the loan amount for lender, title and prepaid items. Matt gives you a Loan Estimate with the exact figures.
How the Home Loan Process Works
- Get pre-approved. Share your income, asset and credit information with Matt and get your pre-approval letter.
- Shop and make an offer. Your EZ agent helps you find the right home and write a competitive offer.
- Apply and lock your rate. Once you are under contract, complete the full application and choose when to lock.
- Appraisal and inspection. The lender orders the appraisal while you complete your home inspection.
- Underwriting and clear to close. You receive your Closing Disclosure at least three business days before closing.
- Close and get your keys. Sign at Trilogy Title Agency, our title partner just down Crocker Road in Westlake, or at their Independence office.
Mortgage FAQ
How much do I need for a down payment in Greater Cleveland?
Less than many buyers think. Conventional loans can start at 3% down for qualified first-time buyers, FHA at 3.5%, and VA and USDA loans can require nothing down for eligible buyers and areas. Putting 20% down avoids private mortgage insurance (PMI) on a conventional loan. Matt can also tell you whether you qualify for Ohio Housing Finance Agency (OHFA) down payment programs.
What is the difference between pre-qualification and pre-approval?
A pre-qualification is a quick estimate based on what you tell a lender. A pre-approval means the lender has reviewed your credit, income and assets, so sellers treat your offer as far stronger. In competitive Cleveland suburbs, most listing agents expect a pre-approval letter with every offer.
How long does it take to get pre-approved?
Often the same day or the next business day once Matt has your pay stubs, W-2s or tax returns, bank statements and permission to pull credit. Start before you tour homes so you can write an offer the moment the right house hits the market.
What goes into a monthly mortgage payment in Cuyahoga County?
Principal and interest, plus property tax, homeowners insurance, any HOA or condo fee, and PMI if you put less than 20% down on a conventional loan. Cuyahoga County property taxes average roughly 1.9% of value per year, but the rate changes by city and school district, so check the exact figure for any home you are considering. The calculator above lets you plug in the real numbers.
Can I buy a condo with an FHA or VA loan?
Yes, if the condo association is approved by FHA or VA, or the unit qualifies under FHA single-unit approval. Conventional condo loans also review the association: its budget, reserves, owner-occupancy, insurance and any litigation. Matt checks a building early so there are no surprises after your offer is accepted.
Do I have to use Matt Sheffey as my lender?
No. You are free to choose any lender. We recommend Matt because he works side by side with our team, answers his phone, and closes on time, but we are happy to work with the lender of your choice and encourage you to compare offers.
Ready to Buy?
Get pre-approved with Matt, then let the EZ Sales Team find your next home. Call our office at 216-916-7778 or start your home search.
Get Pre-Approved with MattTitle & Escrow Services
Matt Sheffey, NMLS #197990. Keller Home Loans is a division of Mutual of Omaha Mortgage, Inc., NMLS ID 1025894, 3131 Camino Del Rio North, Suite 1100, San Diego, CA 92108. Ohio Residential Mortgage Lending Act Certificate RM.804535.000. Equal Housing Lender. Subject to credit approval. This page is for information only and is not a commitment to lend. The EZ Sales Team / Keller Williams Citywide may have a business relationship with Keller Home Loans; you are not required to use any particular lender.